Exploring Senior Reverse Mortgages in Australia

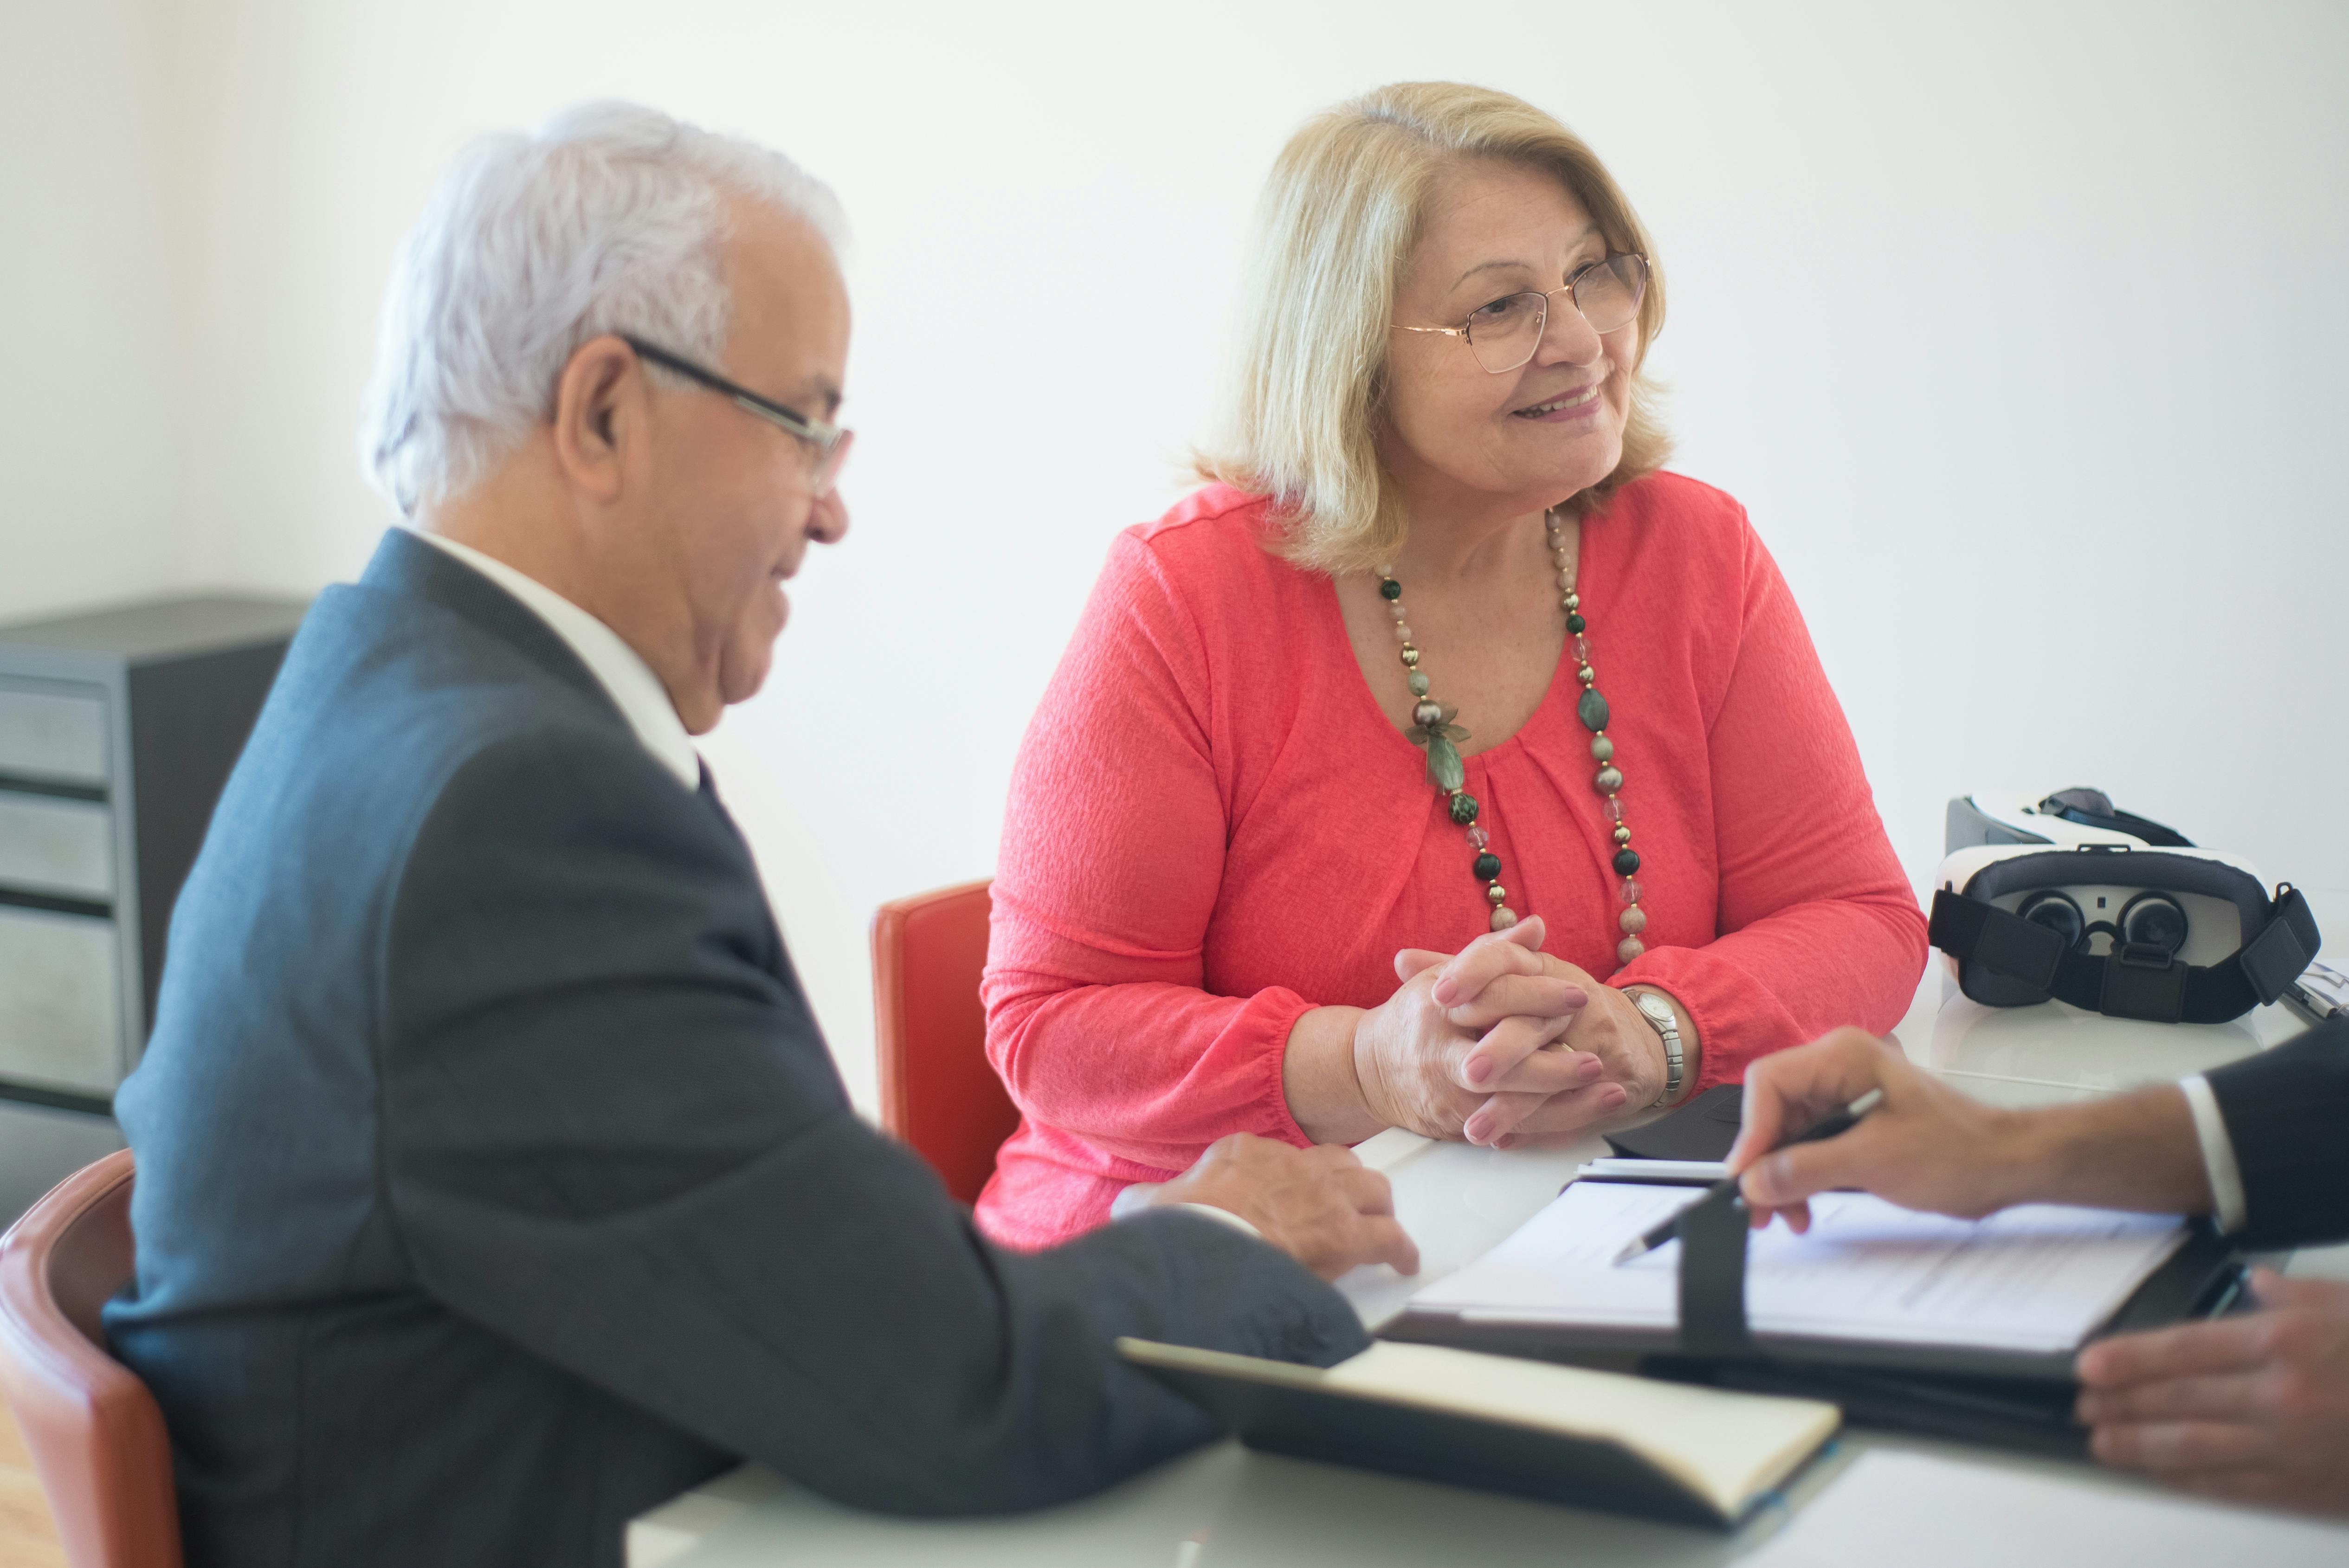
As the Australian population ages, financial stability in retirement becomes an increasingly pressing concern. One of the solutions emerging to address this challenge is the senior reverse mortgage. This financial product allows individuals aged 60 and over to access the equity in their homes, providing a potential lifeline for those who need to supplement their retirement income. Understanding how these reverse mortgages work, their benefits, and the potential pitfalls is crucial for anyone considering this option as part of their financial strategy.
Understanding Senior Reverse Mortgages
A senior reverse mortgage is a type of loan that allows homeowners to convert part of the equity in their home into cash. Unlike a traditional mortgage, there are no regular repayments required. Instead, the loan is repaid when the homeowner sells the house, moves out permanently, or passes away.
Key Features
- Eligibility: Generally available to homeowners aged 60 or older.
- Loan Amount: The amount that can be borrowed is typically based on the age of the youngest borrower and the property’s value.
- No Repayment Until Sale: No need to make repayments until the property is sold.
- Ownership Retained: The homeowner retains ownership of the property.
Benefits of Reverse Mortgages
Reverse mortgages can offer several benefits to seniors looking for financial flexibility. Here are some of the primary advantages:
- Supplemental Income: Provides an additional income stream, which can be used for various expenses, from medical bills to everyday living costs.
- Stay at Home: Allows seniors to continue living in their homes while accessing the equity.
- Flexibility: Offers flexibility in how the funds are used, whether as a lump sum, regular income, or a line of credit.
- No Negative Equity Guarantee: Ensures that the borrower will never owe more than the value of their home when sold.
For those considering this option, it is important to explore advanced guides and tips to fully understand how a reverse mortgage can fit into their retirement planning.
Potential Risks and Considerations
While there are many benefits, there are also important factors to consider before committing to a reverse mortgage:
- Reduced Inheritance: As the loan amount increases over time, the equity left for heirs may decrease.
- Interest Accumulation: Interest on the loan accumulates over time, which can significantly increase the amount owed.
- Impacts on Benefits: A reverse mortgage could affect eligibility for certain pensions or benefits.
It”?s crucial to discover expert strategies here to navigate these risks and consider all aspects of a reverse mortgage.
How to Decide if a Reverse Mortgage is Right for You
Deciding whether to take out a reverse mortgage should involve careful consideration of personal financial goals, retirement plans, and family discussions. Here are steps to guide the decision-making process:
- Financial Assessment: Evaluate current financial needs and how a reverse mortgage could address them.
- Long-Term Planning: Consider how this decision fits into long-term financial and estate planning.
- Professional Advice: Seek advice from financial advisors or mortgage specialists to understand the specific implications.
- Family Discussions: Discuss with family members to ensure alignment and understanding of the impacts on inheritance.
For those ready to delve deeper into this financial product, find out more about this approach to ensure that all aspects are thoroughly considered.
Reverse mortgages present a viable option for many seniors in Australia, offering a means to enhance financial security in retirement. However, like any financial product, it requires careful scrutiny and planning. By leveraging available resources and professional insights, homeowners can make informed decisions about whether a reverse mortgage is the right choice for their circumstances.