The Growth Premium: How Valuations Are Reshaping Medical Device M&A in 2026

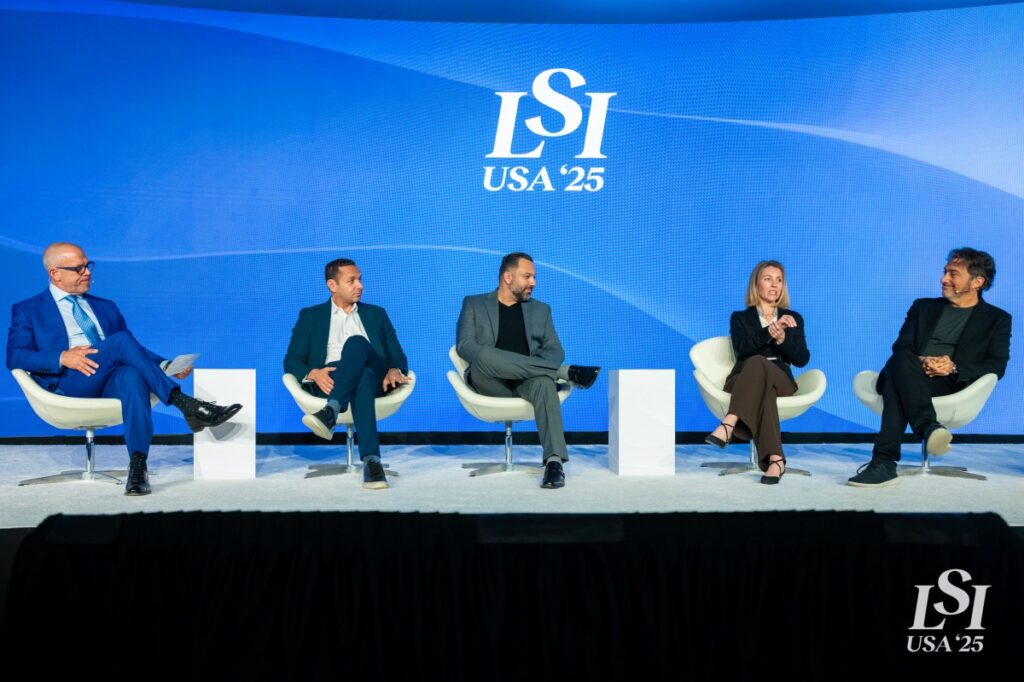
Medical device mergers and acquisitions in 2026 are being driven by one number more than any other: revenue growth. That was the clearest signal from an LSI USA ’26 panel of dealmakers from EY-Parthenon, Medtronic, Edwards Lifesciences, Vensana Capital, and Evercore, who explained where capital is going and what it rewards.
Moderator John Heinbigner (EY-Parthenon) was joined by Chris Eso (Medtronic), Bennett Blau (Evercore), Greg Banker (Vensana Capital), and Chad Rice (Edwards Lifesciences). For more on how corporate venture arms such as Medtronic Ventures fit into that picture, see LSI’s coverage of what corporate VCs want and how they invest.
Why Medtech Trades at a Discount
By operating measures, medtech is healthy: the market grew about 6% in 2025, and procedure volumes and capital spending are solid. Public valuations tell a different story. Blau pointed out that over three years the S&P 500 has risen about 70% and healthcare 20% to 25%, while medtech has fallen 5% to 10%. The result is a sector trading below the market after years at a premium, and an IPO window Blau described as incredibly selective.
How Much Buyers Now Pay for Growth
Because few scaled, high-growth public medtech companies remain, large acquirers cannot rely on the public markets to supply the growth they need.
The math has shifted accordingly. Blau estimated that one point of revenue growth was worth one to one and a half turns of EBITDA before COVID and is worth two and a half to three turns now. In practice, strategics are doing two things at once: buying growth and shedding slower units to lift their overall profile. Blau expects deployment to rise, in forms that look different from past cycles.
Steady Deal Flow, Even When It Is Quiet
Headline deal counts understate activity. Eso said Medtronic closes five or six acquisitions annually, most too small to announce, alongside minority stakes and structured deals.
Edwards Lifesciences keeps its focus on structural heart disease, often investing early and acquiring once fit is proven. That pattern matters for valuation: early strategic investment can set up a later acquisition on terms that work for both sides.
Where AI Fits in Valuation
Buyers named interventional, vascular, neuro, and robotics as active categories. AI can command a premium, Blau said, but only when it is tied to clinical impact.
Eso and Rice both said AI must attach to a therapy or device to be worth paying for, and Banker observed that the AI companies drawing interest are FDA-regulated, physician-directed, and embedded in clinical workflow.
What Earns the Premium
Banker’s criteria for a must-buy asset are the same ones that drive price: solving a problem the buyer or its customers care about, filling a gap in the buyer’s portfolio, and creating scarcity or competitive tension.
Rice added that premature commercialization can lower value if it exposes weaknesses in quality, cost of goods, or supply chain.
Eso and Blau both emphasized trust. Transparent founders move through diligence faster, and the best deals feel like partnerships.
Capital Outlook for the Next 18 Months
Eso said Medtronic expects to deploy upwards of another $2 billion to $3 billion over the next 12 to 18 months. Blau sees healthcare gaining favor as a more defensible sector than parts of tech and software, which could widen the pool of capital.
For founders, the valuation lesson is direct: growth, fit, and credibility set the price.
Key Takeaways
- Medtech’s operating fundamentals are stronger than its public valuations suggest.
- A point of revenue growth now earns two and a half to three turns of EBITDA, up from one to one and a half before COVID.
- Medtronic and Edwards stay active through smaller, often unannounced deals.
- AI earns a valuation premium only when linked to clinical results.
- Premium valuations go to companies that solve real problems, fill buyer gaps, and build trust early.
Medical device M&A in 2026 favors quality over volume. Capital is available and buyers are deploying it, but the premium goes to companies that can prove their technology works and creates lasting strategic value. LSI USA ’27, March 15 to 19, 2027, in Dana Point, California, is where many of those buyers and companies meet.
Frequently Asked Questions
Why are medtech valuations lower than the broader market?
Medtech’s operating fundamentals are healthy, but public investors have favored other sectors. Over three years, the S&P 500 rose about 70% while medtech fell 5% to 10%, according to Evercore’s Bennett Blau.
How much is revenue growth worth in medtech M&A?
Blau estimated that each point of revenue growth is now worth about two and a half to three turns of EBITDA, compared with one to one and a half turns before COVID.
Will medtech M&A activity increase in 2026?
Panelists at LSI USA ‘26 expected capital deployment to rise, with Medtronic alone planning to deploy upwards of $2 billion to $3 billion over 12 to 18 months, though deal structures will differ from past cycles.